| Title |
Browning Arms Company Collection, Box 012, Folder 07 |
| Creator |
Birdsell, Wayne; Browning, Val A., 1895-1994; Rafter, John R.; FN (Firm : Belgium); Schroeder Freres; Zinn, Harry A.; United States. Bureau of Customs; Browning, John Val; Mattlet, Ernest; Briggs, William M.; Browning, Marriner Bigelow; Goddard, Grant F.; Kinkade, Byron; Senden, F. Raymond; United States. Embassy (Belgium); Union of Gunsmith Retailers of Belgium |
| Description |
Exchanges and documentation regarding customs and importation, with John R. Rafter as primary creator. Includes drafts of affidavits. |
| Subject |
Firearms industry and trade--United States; Firearms industry and trade--Utah; Browning Arms Company; Business enterprises--Utah--Ogden--History |
| Digital Publisher |
Digitized by Special Collections & University Archives, Stewart Library, Weber State University. |
| Date Digital |
2026-06 |
| Date |
1951; 1952; 1953; 1954 |
| Medium |
correspondence; documents; financial records; legal records |
| Spatial Coverage |
Washington, D.C., United States; New York City, New York, United States; Denver, Denver County, Colorado, United States; Herstal, Liège, Wallonia, Belgium; Ogden, Weber County, Utah, United States; St. Louis, Missouri, United States; Liège, Wallonia, Belgium; Brussels, Brussels-Capital Region, Belgium |
| Type |
Text |
| Conversion Specifications |
Archived TIFF images were scanned with an Epson Expression 13000XL scanner. Digital images were reformatted in Photoshop. |
| Language |
eng; fra |
| Rights |
Materials may be used for non-profit and educational purposes; please credit Special Collections & University Archives, Stewart Library, Weber State University. For further information:  |
| Sponsorship/Funding |
Funding generously provided by the Val A. Browning Charitable Foundation. |
| Source |
Browning Arms Company Collection, MS492, Box 12, Folder 7, Special Collections & University Archives, Stewart Library, Weber State University. |
| Format |
application/pdf |
| ARK |
ark:/87278/s6mmbx9n |
| Setname |
wsu_ba |
| ID |
194196 |
| Reference URL |
https://digital.weber.edu/ark:/87278/s6mmbx9n |
| Title |
Page 65 |
| OCR Text |
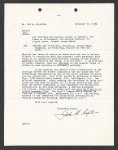
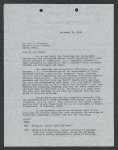
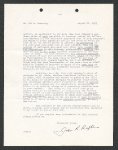
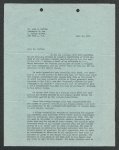
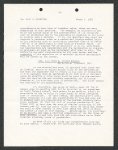
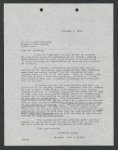
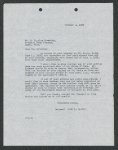
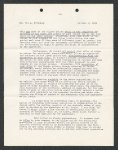
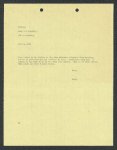
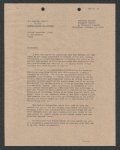
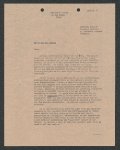
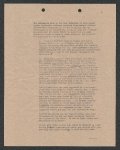
Show Mr. John V. Browning the totel output. selling prices of March In the the 1953 Hence, they usually become a part all units of the total output which duced during the expense period the sale of all such units. ing and covered 3, case of a new and of the were pro- are usually recovered product, however, whose from design- development involved an expense. which can not be reby the manufacturer from the sale of its output during period in which such expense was I believe, to charge such expense which the manufacturer expects to incurred, it is customary, to each such new product | make and sell during a period which will permit the recovery of such expense. in other words, that kind of expense becomes a part of the selling prices of future output of the new product and is recovered from future sales thereof. Certainly, cost of production made by the the sale of the not chargeable lot of the manufacturer, unless it is fully first lot. Nor amount would pay duty dutiable value The is it new than is properly in full product to the which is recoverable properly any greater amount than to amount is recoverable from Incidentally, if that dutiable value of the 11 greater is first the first lot in less the greater first Lot. in it the the of from chargeable any the kind of expense were included sample guns in question in any chargeable to them, your company again on that of its future excess amount, as a part of importations of such guns. third of element to later lot, unsale of the statutory "cost of the production" is the cost of all containers and coverings and all other costs, charges and expenses incident to placing the merchandise in condition packed ready for shipment to the United States. As applied to the il sample of labor in packing them the cost of the guns in question, this means the cost for shipment to the United States plus containers and coverings in which packed. they were so : The fourth element of statutory "cost of production" is an "addition for profit" above the sum of its first and second elements. That addition must be not less than 5% of the total of those two elements and must be equal (in percentage of that total) to the profit which is ordinarily added to like elements of the cost of production general character by manufacturers merchandise in question is made. same term of merchandise of the same in the country where the The term "merchandise of general character", as thus used, "such or similar merchandise", as the is much broader than the employed in items 1 and 2 |
| Format |
application/pdf |
| Setname |
wsu_ba |
| ID |
194261 |
| Reference URL |
https://digital.weber.edu/ark:/87278/s6mmbx9n/194261 |