| Title |
Browning Arms Company Collection, Box 012, Folder 07 |
| Creator |
Birdsell, Wayne; Browning, Val A., 1895-1994; Rafter, John R.; FN (Firm : Belgium); Schroeder Freres; Zinn, Harry A.; United States. Bureau of Customs; Browning, John Val; Mattlet, Ernest; Briggs, William M.; Browning, Marriner Bigelow; Goddard, Grant F.; Kinkade, Byron; Senden, F. Raymond; United States. Embassy (Belgium); Union of Gunsmith Retailers of Belgium |
| Description |
Exchanges and documentation regarding customs and importation, with John R. Rafter as primary creator. Includes drafts of affidavits. |
| Subject |
Firearms industry and trade--United States; Firearms industry and trade--Utah; Browning Arms Company; Business enterprises--Utah--Ogden--History |
| Digital Publisher |
Digitized by Special Collections & University Archives, Stewart Library, Weber State University. |
| Date Digital |
2026-06 |
| Date |
1951; 1952; 1953; 1954 |
| Medium |
correspondence; documents; financial records; legal records |
| Spatial Coverage |
Washington, D.C., United States; New York City, New York, United States; Denver, Denver County, Colorado, United States; Herstal, Liège, Wallonia, Belgium; Ogden, Weber County, Utah, United States; St. Louis, Missouri, United States; Liège, Wallonia, Belgium; Brussels, Brussels-Capital Region, Belgium |
| Type |
Text |
| Conversion Specifications |
Archived TIFF images were scanned with an Epson Expression 13000XL scanner. Digital images were reformatted in Photoshop. |
| Language |
eng; fra |
| Rights |
Materials may be used for non-profit and educational purposes; please credit Special Collections & University Archives, Stewart Library, Weber State University. For further information:  |
| Sponsorship/Funding |
Funding generously provided by the Val A. Browning Charitable Foundation. |
| Source |
Browning Arms Company Collection, MS492, Box 12, Folder 7, Special Collections & University Archives, Stewart Library, Weber State University. |
| Format |
application/pdf |
| ARK |
ark:/87278/s6mmbx9n |
| Setname |
wsu_ba |
| ID |
194196 |
| Reference URL |
https://digital.weber.edu/ark:/87278/s6mmbx9n |
| Title |
Page 121 |
| OCR Text |
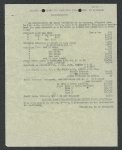
Show Indirect Expenses Heat, Light and powers Freight and cartage inward; under. direct materials Rent of factory building or to manufacturing, (CAD 308)3_ Insurance — fire and liabilitys Maintenance, repairs Depreciation of (GAD 305)3 Taxes on plant out F; and of profits), aS a Marketing Administrative and come ns Expenses Menai Mees” Somme Meese gat expenses Expenses unusual The term they as i Mocs isp WaT Officers’ salaries Office salaries Executives! expenses Auditing expenses Legal expenses Administrative office expenses Usual income taxes, equipment {CAD 305) Expenses office and smal Sales renewals} buildings not (but: Commissions Salesmen's salaries Salesmen's expenses Advertising Traveling and factory ane Monae Monae” Mi (CAD 305) Fxpenses “usual general expense" excludes the unusual If there be any ys question whether one or TD 48860 Dept. more items of expense are usual. or unusual, all the facts should be reported in order that the apnraiser may be. in 2 position to decide how to treat such items. % Cost of all Containers. tThe cost-of all containers and coverings of whatever nature, nd ali otner costs, charges, and expenses iricident to placing the articular merchandise under consideration in condition, ong M, for shipment to United States” the TA) ( 102¢£)€3) be & should nd should include any freight or delivery charge acéruing . product. for transportation to the principal. market if the lat In this connection the-n eng st a distance from the factory. applica ble to foreign and export Values are also applicable to’ of apediavi on: Profit The adat yin for profit under sub-section ordinarily is manufacturer in question adds, (4) is the “by manufacturers added which profit or. pro- ‘ducers in ge country of manufacture or production who are engaged in the production or manufacture of merchardise of the same @lass or kind. "The prefit which the particular eriterion IGPA), for the determination although ak de? of the fal evidence See i2y 252. the profits merchandise of the , mn eretere? sole (TD 44679 made by the manufac constitute some substan- ordinSavity invoived profit is not the of the profit to be added. CCPAS TD 4637 | /The words cost |
| Format |
application/pdf |
| Setname |
wsu_ba |
| ID |
194317 |
| Reference URL |
https://digital.weber.edu/ark:/87278/s6mmbx9n/194317 |