| Title |
Browning Arms Company Collection, Box 012, Folder 07 |
| Creator |
Birdsell, Wayne; Browning, Val A., 1895-1994; Rafter, John R.; FN (Firm : Belgium); Schroeder Freres; Zinn, Harry A.; United States. Bureau of Customs; Browning, John Val; Mattlet, Ernest; Briggs, William M.; Browning, Marriner Bigelow; Goddard, Grant F.; Kinkade, Byron; Senden, F. Raymond; United States. Embassy (Belgium); Union of Gunsmith Retailers of Belgium |
| Description |
Exchanges and documentation regarding customs and importation, with John R. Rafter as primary creator. Includes drafts of affidavits. |
| Subject |
Firearms industry and trade--United States; Firearms industry and trade--Utah; Browning Arms Company; Business enterprises--Utah--Ogden--History |
| Digital Publisher |
Digitized by Special Collections & University Archives, Stewart Library, Weber State University. |
| Date Digital |
2026-06 |
| Date |
1951; 1952; 1953; 1954 |
| Medium |
correspondence; documents; financial records; legal records |
| Spatial Coverage |
Washington, D.C., United States; New York City, New York, United States; Denver, Denver County, Colorado, United States; Herstal, Liège, Wallonia, Belgium; Ogden, Weber County, Utah, United States; St. Louis, Missouri, United States; Liège, Wallonia, Belgium; Brussels, Brussels-Capital Region, Belgium |
| Type |
Text |
| Conversion Specifications |
Archived TIFF images were scanned with an Epson Expression 13000XL scanner. Digital images were reformatted in Photoshop. |
| Language |
eng; fra |
| Rights |
Materials may be used for non-profit and educational purposes; please credit Special Collections & University Archives, Stewart Library, Weber State University. For further information:  |
| Sponsorship/Funding |
Funding generously provided by the Val A. Browning Charitable Foundation. |
| Source |
Browning Arms Company Collection, MS492, Box 12, Folder 7, Special Collections & University Archives, Stewart Library, Weber State University. |
| Format |
application/pdf |
| ARK |
ark:/87278/s6mmbx9n |
| Setname |
wsu_ba |
| ID |
194196 |
| Reference URL |
https://digital.weber.edu/ark:/87278/s6mmbx9n |
| Title |
Page 119 |
| OCR Text |
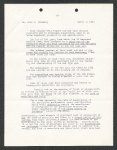
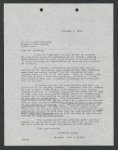
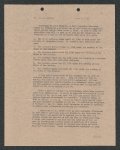
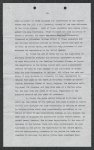
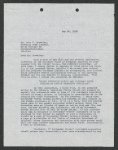
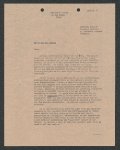
Show Where the manufacturer is obliged to pay a ales or consumption tax on the sale of the article mn the home market, the manner of assessment and ll other facts pertaining thereto should be ascer— 2 Aeete iil ained and reported in de in order to enable the appraiser to take whatever Actionhe deems necessary, “Note GAD 305. 2 A tax paid at the souree becomes in the ordinary course of business a4 part-of the cost of the goods. TD: 40731. COA, : Bub where unfinished material is imported into. a foreign country for finishing, and is ex- empted from import duties. on the condition that he finished cloth be exported, the unpaid tax S not part of the cost..of spl du alin he TD 40989 .CC. where the manufacturer: has sor an import duty on imported ture duty of is the articles under Sinabduvetl on t he considered a part of the cost of materi+ materials used.in the als. Where the exported facturéd in bond without article has the payment. the the imported materials, sidered as a part GA), in ota but the order duty facts should been manuof duty on cannot be of the material ‘thatthe manufac- con- cost (TD 40989 be renorted in detail appraiser may be fully informed. v4 Labor when Costs: of labor may Labor is paid on a piece-work be tails little difficulty. that the manufacturer has ascertained in bais, varlous this ways. usually In other cases it. may be determined cost of labor en- found by tests. Génerally speaking, methods of computing labor costs, which are actually used by the manufacturer and found satisfac-— tory by him, may be accepted. Compensation paid to talent for the production of ‘phonograph records is part. of the cost of fabrication. TD. 36505 CCA cludes Cost of production of ‘siamovtel the artists: work and labor. eae in= figs GA < Serial Importations In the ppoauut len of certain articles, such as blue- prints and before the be made to unbound books, considerable costs are incurred first print or copy can be. made. A shiprent may the United States: consisting of all or part of the lot first produced, and then, at later times, future shipments may be made out of lots subsequently produced. Very often, when the first lot is produced, the manufacturer does not know whether additional copies will be made; or, if soy how many. For decisions relating to blueprints in cost of production FD 36505 cases see CID 286/40, 678/403 1010/40 Royalties of The question of whether royalties are product! ion is. to be decided by the same foreign or.export cost of production value. Where a royalty included in cost e applying to rules is part (1) aif paid by. the manufacturer, of the it is generslsy a cost.of labor, and (2) if paid to the. manufacturer, it. is part of his profit Whenever the manufacture or production of the iS edkand ise involves the payment of royalties or license fees; all the facts in connection therewith should be reported in detail... For cases in which royalties were part of cost of. production see TD 31903 Dept. 3 CAD A2. |
| Format |
application/pdf |
| Setname |
wsu_ba |
| ID |
194315 |
| Reference URL |
https://digital.weber.edu/ark:/87278/s6mmbx9n/194315 |