| OCR Text |
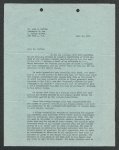
Show Mr. John V. Browning a in made 1953 if they had of (December 13, 1952) Incidentally, in the experimental of of course usual the in been date the preceding production period normal exportation their 3, guns, those of manufacture the in incurred March business. there guns, sample those fitting to the for their for assembling your which to salaries done was which and engineers" which regular and fitting those suns. F.W. Myers Life v. Assurance decided by Co. Customs & of in addition engineers received States (Sun officers they and United those services, were paid compensation extra Co., and executives unless, refers, assembling the for paid “highly the by letter of production labor of cost no was Ine. Canada), Court,Jan.1, 1932;C.R. 2227. On the other hand, in the production of those guns, as contemplated by the statute, there is a cost of labor for that assembling and fitting, in an amount represented by the time ordinarily required for that work at the wages ordinarily payable therefor. : the usual cost such The second element of statutory general expenses in the case of factory overhead These expenses. not only in my opinion, including, chandise, expenses but also selling and administrative materials the statute to amount must expenses of is not Here again, concerned with what the cost per cent of however, you will note that not with what is 10 than less labor. and production is similar mer- of or is - usual to the usual element the limitation of this In short, unusual. from the statutory cost of production excludes expenses general of the sample guns in question any general expenses (whether which were unusual, or administrative) selling factory overhead, from what would have been inin kind or amount different i.e., curred if the usual those guns had been course of business. produced in the ordinary way in - Under the heading of “usual general expenses”, there- fore, would be all ordinary expenses which are not traceable and directly chargeable to the production of any particular guns, @.g., rent, light, heat, power, depreciation of machinery and equipment, storage, etc., as well as salaries or wages for services other than labor in making or packing guns. As a rule, such expenses are spread over the manufacturer's during the period in which they are incurred and to ea@h unit of production in a ratio which each whole output are chargeable unit bears to |