| OCR Text |
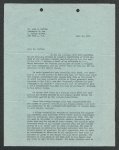
Show John Mr. 1953 3, March Browning V. sideration of this matter in the light of the additional facts which you will bring to his attention, may finally decide that a statement of their cost of production is unnecessary for appraisement purposes. In 1930, Act of dise connection, this all by thereof to appraise estimating or ascertaining "hy 500(a)(1) appraiser the directs Section the Tariff merchan- imported the value and means ways reasonable of in his power, any statement of cost or cost of production in any invoice, affidavit, declaration, or other document to the con- notwithstanding;" trary (underlining mine). Under that section and on all of the facts which will presently be available to him, the appraiser, in my opinion, may reasonably and properly appraise those 11 guns at the price of $150.each at which they were sold to your company, as representing either their “export Those mental purposes else would have that is those sold value" or their so, your company guns, and, in my opinion, the company is their “export to your The cited authority volved sample books was Co..v. is of the only Of Gourse, one buyer is raise it to sufficient. production". a value potential price at purchaser which they States, 9 Ct. Gust. Appls. 280. the leading case on this wall paper for which the They which were they point. it inLloyd Company held were to have sold to if the price at which merchandise too low to satisfy the appraiser, which, Harry in his Garbeyv. 24. Furthermore, though production is usually opinion United G.0.P.A. of were value". United was the only potential purchaser. properly appraised at the price at one buyer. only of 11 guns were sold to your company "for experiand as samples only;" and, I believe, nobody bought those guns for those purposes only. If Lloyd to "cost as an expert, is he been that sold may is States, (Customs) sé. an itemized statement of statutory requested by the appraiser for an |