| Title |
Browning Arms Company Collection, Box 012, Folder 07 |
| Creator |
Birdsell, Wayne; Browning, Val A., 1895-1994; Rafter, John R.; FN (Firm : Belgium); Schroeder Freres; Zinn, Harry A.; United States. Bureau of Customs; Browning, John Val; Mattlet, Ernest; Briggs, William M.; Browning, Marriner Bigelow; Goddard, Grant F.; Kinkade, Byron; Senden, F. Raymond; United States. Embassy (Belgium); Union of Gunsmith Retailers of Belgium |
| Description |
Exchanges and documentation regarding customs and importation, with John R. Rafter as primary creator. Includes drafts of affidavits. |
| Subject |
Firearms industry and trade--United States; Firearms industry and trade--Utah; Browning Arms Company; Business enterprises--Utah--Ogden--History |
| Digital Publisher |
Digitized by Special Collections & University Archives, Stewart Library, Weber State University. |
| Date Digital |
2026-06 |
| Date |
1951; 1952; 1953; 1954 |
| Medium |
correspondence; documents; financial records; legal records |
| Spatial Coverage |
Washington, D.C., United States; New York City, New York, United States; Denver, Denver County, Colorado, United States; Herstal, Liège, Wallonia, Belgium; Ogden, Weber County, Utah, United States; St. Louis, Missouri, United States; Liège, Wallonia, Belgium; Brussels, Brussels-Capital Region, Belgium |
| Type |
Text |
| Conversion Specifications |
Archived TIFF images were scanned with an Epson Expression 13000XL scanner. Digital images were reformatted in Photoshop. |
| Language |
eng; fra |
| Rights |
Materials may be used for non-profit and educational purposes; please credit Special Collections & University Archives, Stewart Library, Weber State University. For further information:  |
| Sponsorship/Funding |
Funding generously provided by the Val A. Browning Charitable Foundation. |
| Source |
Browning Arms Company Collection, MS492, Box 12, Folder 7, Special Collections & University Archives, Stewart Library, Weber State University. |
| Format |
application/pdf |
| ARK |
ark:/87278/s6mmbx9n |
| Setname |
wsu_ba |
| ID |
194196 |
| Reference URL |
https://digital.weber.edu/ark:/87278/s6mmbx9n |
| Title |
Page 68 |
| OCR Text |
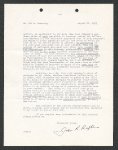
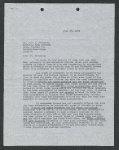
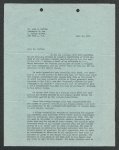
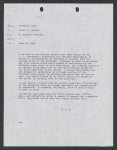
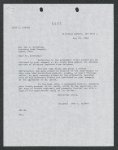
Show Mr. John V. Browning March 3, 1953 appraisement at that kind of dutiable value, there are many exceptions to that practice. For example, an importation may be of too little value or the ascertainment of its statutory cost of production may be to require such a showing. too expensive if so, the importer's or a purchase price in relation to its value appraiser may adopt the restricted foreign market as its statutory cost of production, provided that fied it is at least equal to that kind of dutiable deed, it is not unusual for an appraiser to do so, the importations are ly produced, so long latter is authority will be by the Mrs. In no substantial and the merchandise is regularas the Government will lose no duty. The the main consideration of the appraiser so to upheld foreign, price he is satisvalue. [Ineven where in all such cases; and the appraise imported merchandise courts. G.P. Snow the above-cited export or United v. United ou C.C.P.A. States, (Customs) 319. case, it appeared that there was States value of the merchandise, and that the appraiser had to resort to its cost of production. It also appeared that he appraised it at that kind of dutiable value by adopting a price which would be paid for the merchandise and that he did not consider separately the different 3 elements of its statutory cost of production. The court upheld the validity of If, sample guns the appraisement. therefore, the price of question will not accepted in as their "export value", that acceptable to him as being at cost of production. davit indicates is simpler than matic shotgun; To (1) the (2) that be $150.- each by for the the ll appraiser price,in my opinion, should be least equal to their statutory effect, the manufacturer's affi- that the construction of that new type gun construction of the regular Browning auto- that the cost the facts that the of regular production of the former will be less than the cost of regular production of the latter; and (3) that the price ($150.- each) at which the former was sold to your company is more than twice the price at which the latter is sold to your company. Additionally, the appraiser, as _an expert, may make a physical comparison of the two types of guns referred to and thus draw his own conclusions as to their relative statutory costs of production. to this In view matter, I of all trust and circumstances appraiser will relating finally decide |
| Format |
application/pdf |
| Setname |
wsu_ba |
| ID |
194264 |
| Reference URL |
https://digital.weber.edu/ark:/87278/s6mmbx9n/194264 |