| Title |
Browning Arms Company Collection, Box 012, Folder 07 |
| Creator |
Birdsell, Wayne; Browning, Val A., 1895-1994; Rafter, John R.; FN (Firm : Belgium); Schroeder Freres; Zinn, Harry A.; United States. Bureau of Customs; Browning, John Val; Mattlet, Ernest; Briggs, William M.; Browning, Marriner Bigelow; Goddard, Grant F.; Kinkade, Byron; Senden, F. Raymond; United States. Embassy (Belgium); Union of Gunsmith Retailers of Belgium |
| Description |
Exchanges and documentation regarding customs and importation, with John R. Rafter as primary creator. Includes drafts of affidavits. |
| Subject |
Firearms industry and trade--United States; Firearms industry and trade--Utah; Browning Arms Company; Business enterprises--Utah--Ogden--History |
| Digital Publisher |
Digitized by Special Collections & University Archives, Stewart Library, Weber State University. |
| Date Digital |
2026-06 |
| Date |
1951; 1952; 1953; 1954 |
| Medium |
correspondence; documents; financial records; legal records |
| Spatial Coverage |
Washington, D.C., United States; New York City, New York, United States; Denver, Denver County, Colorado, United States; Herstal, Liège, Wallonia, Belgium; Ogden, Weber County, Utah, United States; St. Louis, Missouri, United States; Liège, Wallonia, Belgium; Brussels, Brussels-Capital Region, Belgium |
| Type |
Text |
| Conversion Specifications |
Archived TIFF images were scanned with an Epson Expression 13000XL scanner. Digital images were reformatted in Photoshop. |
| Language |
eng; fra |
| Rights |
Materials may be used for non-profit and educational purposes; please credit Special Collections & University Archives, Stewart Library, Weber State University. For further information:  |
| Sponsorship/Funding |
Funding generously provided by the Val A. Browning Charitable Foundation. |
| Source |
Browning Arms Company Collection, MS492, Box 12, Folder 7, Special Collections & University Archives, Stewart Library, Weber State University. |
| Format |
application/pdf |
| ARK |
ark:/87278/s6mmbx9n |
| Setname |
wsu_ba |
| ID |
194196 |
| Reference URL |
https://digital.weber.edu/ark:/87278/s6mmbx9n |
| Title |
Page 118 |
| OCR Text |
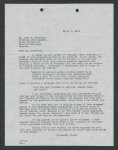
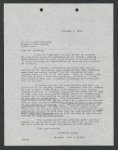
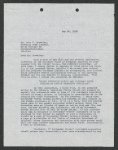
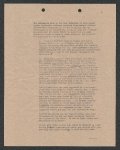
Show The officer conduction the inquiry must be guided largely by whatever evidence of the cost of production he is able toe obtain. Numerous manufacturers calculate or estimate their costs largely by rule-of-thumb methods which may be based upon the results obtained during their business ex- perience rather The, items than separate forming upon actual itemization part of the cost figures. or, breakdown elements of of cost the various is desirable, but only the four enumerated statutory elements are absolutely required. Any consolidation of the four elenents is not permissible. TD ABIL CCPAs 48767 CCPA, B6911 COPA. However, if figures in creater detail are obtainable, such detailed figures should be obtained and reported. Cost of Materials, This parts Fabrication element is usually ete. broken -— materials and.Jabor. TD Some articles are made of 4 are made by joining down into its 4é900 CCPA. Single material or combining geveral principal Tt materi eee fy the cost: of materials; it is necessary to ascertain wist materials (2) (3): what the unit were used, how cost of each much was. of each was (1) used, This sometimes and entai inguiry as to a formula or other trade secret which the manufacturer does not want incorporatedin the report. In such case, the formula or secret should not be reported or even retained. It is sufficient to report that tne manufactur- records showed that the materials for making so many of the imoorted merchandise cost so much, and.to ex-= nhe reason for not giving more detailed information. Care should be exercised to obtain the costs of all materials used in the manufacture of the imported article and inquiry should always be made as to whether the Uni bed States importer. or purchaser furnished any of the materials Items of cost should not be eonfinedto those actually paid for by the manufacturer himself. It is proper to include the cost. of plans or designs used in pretietne the imported article regardless of the country of their origin and whether they “were paid for by the manufacturer or the importer. TD 41503. GA wees 7 | wnen @ contractor ublets, all, or a portion, of his: order the. price char; tor included in cost is ting the shipped. cost:of the by the of production subcontrac- materials of the in-compu- merchardise other the cost of transportation, insurance and charges, incident..to the purchase and @liv— ery to the place of manufacture of "materials" whithin the meaningof section 402(f)(1) tariff of TD 39981 Beh» enter into the cost of the production. -CCCl Af The “cost of materials" is the amount actually paidefor them, not their market value. - The enuestion ise What is the cost to the manufacturer at the place of manufacture, of all materials en- tering into the In the finished product case of raw Silk 7? CAD 103 shipped from the Uni- ted States to a foreign country; where it was thrown. and. dyed; and then shipped back to the United States, the cost of materials was the cost: of, the raw silk in the United States, plus all costs ineurred in transporting the raw silk to the foreign countrys The dost of fabrication was the amount paid for dyeing and throwing, including the threwster's and dyer's general expenses and. profit. TD 399681 COAL /where the |
| Format |
application/pdf |
| Setname |
wsu_ba |
| ID |
194314 |
| Reference URL |
https://digital.weber.edu/ark:/87278/s6mmbx9n/194314 |